UK Gambling Sector Reports £17.5 Billion Gross Gambling Yield for 2025-2026 Financial Year
Written by Taylor Griffin · Sep 18, 2026
UK Gambling Sector Reports £17.5 Billion Gross Gambling Yield for 2025-2026 Financial Year
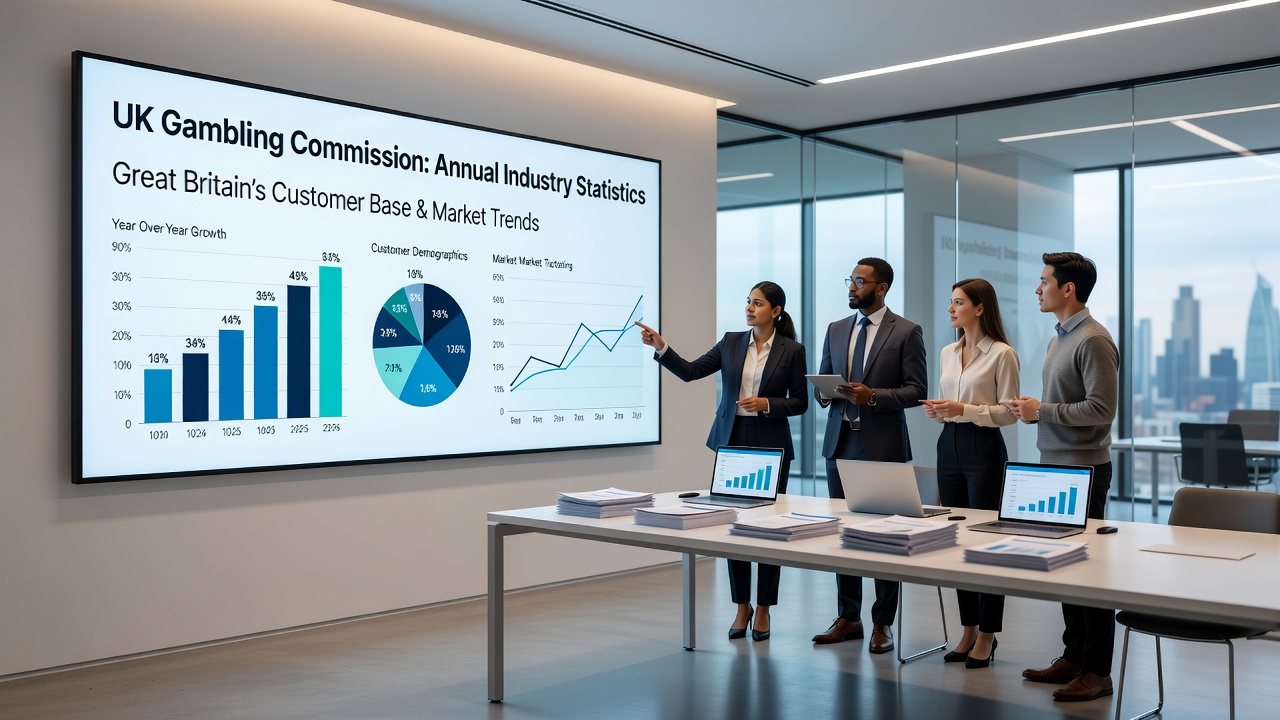
The UK Gambling Commission has published its annual industry statistics covering the financial year from April 2025 to March 2026, and the numbers show Great Britain’s customer-facing gambling sector produced £17.5 billion in Gross Gambling Yield, which represents a 4.4% rise compared with the previous period. Remote activities drove most of that expansion, while certain land-based segments experienced modest contractions yet still contributed to the overall total. Observers note the figures exclude lottery operations in some breakdowns, yet the core data remains consistent across the reported metrics.
Remote Activities Lead Expansion
Online platforms accounted for the largest share of the increase, with remote casino products generating £5.7 billion in GGY, an advance of 14.8% year on year. Within that category, slots alone reached £4.8 billion, underscoring how digital slot play continues to expand its footprint. The Gambling Commission’s industry statistics confirm that remote betting and gaming together outpaced every other channel during the twelve-month span. Data indicates this shift aligns with broader consumer preferences for accessing games through mobile and desktop devices rather than visiting physical venues.
Land-Based Premises Show Mixed Results
Traditional betting shops and casinos recorded slight declines in GGY, reflecting ongoing pressure on high-street locations. Yet gaming machines located in arcades delivered stronger performance, climbing 10.7% compared with the prior year. These gains occurred even as overall land-based premises faced reduced footfall in several regions. Figures reveal that arcade machine revenue benefited from updated game offerings and improved venue management practices, which helped offset wider softness in other terrestrial segments.
When lottery operations are removed from the calculation, the remaining gambling activities produced £13.2 billion in GGY, up 4.7%. This adjusted total isolates the performance of betting, casino, and machine-based products, giving a clearer view of commercial operator results. Researchers have observed that the 4.7% growth rate exceeds the headline 4.4% figure, highlighting how lottery contributions moderated the overall percentage change.
Breakdown of Key Product Categories
Online casino revenue, which includes slots, table games, and live dealer formats, reached the £5.7 billion mark after posting double-digit growth. Slots formed the dominant sub-segment at £4.8 billion, leaving the balance to other casino-style games. Remote sports betting also contributed meaningfully, although its growth rate trailed the casino channel during the same period. Industry analysts point to regulatory changes around safer gambling tools and advertising restrictions as factors that shaped spending patterns without halting overall expansion.
Land-based gaming machines outside arcades, such as those in betting shops and adult gaming centres, showed more modest movement. The 10.7% arcade gain stands out because it reversed a multi-year trend of flat or declining machine revenue in similar venues. Venue operators attribute the improvement to refreshed machine fleets and targeted promotions that encouraged repeat visits. Meanwhile, high-street betting shops continued to experience gradual erosion of GGY, consistent with longer-term migration toward digital channels.
Context Within Broader Market Trends
The 4.4% headline increase follows several years of recovery after pandemic-related disruptions. Remote channels have now established a structural advantage, capturing the majority of new customer acquisition and session activity. Data shows that operators have invested heavily in app development, payment options, and responsible gambling features, all of which supported sustained engagement. Those who track regulatory filings note that licensing conditions around anti-money-laundering checks and age verification remained stable, providing a predictable operating environment.
September 2026 marks the release window for these statistics, allowing stakeholders to compare performance against the 2024-2025 baseline. The report covers all licensed operators active in Great Britain and aggregates GGY across remote, non-remote, and machine-based activities. Exclusions for lottery products appear only in the supplementary £13.2 billion line, while the primary £17.5 billion total incorporates every customer-facing segment the Commission oversees.
Conclusion
The latest annual statistics from the UK Gambling Commission document a market that expanded to £17.5 billion in GGY, driven primarily by remote casino and slot products while certain land-based segments posted smaller gains or modest declines. Online casino revenue reached £5.7 billion after rising 14.8%, with slots contributing £4.8 billion of that total. Arcade gaming machines advanced 10.7%, offsetting softness elsewhere in the terrestrial estate. When lotteries are excluded, the adjusted figure stands at £13.2 billion, up 4.7%. These numbers reflect activity across the financial year ending March 2026 and provide a factual snapshot of sector performance under current regulatory conditions.